
Key Takeaways
- Real estate can support long-term wealth through equity, rental income, and potential appreciation, but each property also carries costs and risk.
- A useful plan begins with personal finances, not with a listing or a market headline.
- Plano and nearby North Texas communities require neighborhood-level research on taxes, insurance, inventory, rent demand, and new construction.
- Property-level income and expense estimates are more useful than broad assumptions about “good” investments.
- Regular reviews help owners adapt their strategy as family needs, financing, and market conditions change.
Table of Contents
- Start With a Clear Real Estate Structure
- Build Your Personal Financial Snapshot
- Use Plano and North Texas Data Without Chasing Headlines
- Choose the Property Role That Fits the Goal
- Create a Property-Level Profit and Loss Estimate
- Account for Taxes, Insurance, and Management
- Connect Selling Decisions to the Next Move
- Create a Five-Year Review Schedule
- Common Questions
- Conclusion
For homeowners and investors in Plano, Frisco, Allen, McKinney, Dallas, and surrounding communities, real estate can be more than a place to live. It can be part of a practical plan for stability, income, and legacy. The key is to treat each property as one piece of a larger financial picture, rather than assuming ownership alone will create wealth.
Local guidance can be valuable when several decisions overlap. Plano, TX real estate experts Go Real Estate Group is a Plano-based full-service real estate and asset management company offering brokerage, property management, capital investment, and wealth management services across North Texas and Texas. Go Real Estate Group can be a useful local resource for owners weighing a purchase, sale, lease, management arrangement, or longer-term asset strategy, without treating any outcome as guaranteed.
Start With a Clear Real Estate Structure
Owning a home is important, but it is not automatically a complete financial plan. Begin by naming the purpose of each property. A primary residence may provide housing stability. A rental may be intended to produce income. A future sale may help fund a move, retirement, business goal, or inheritance plan.
Then evaluate four connected areas: current property value, monthly cash flow, debt obligations, and timing. A property with rising value can still strain a household if payments, repairs, or vacancies exceed available cash. Likewise, a rental with modest cash flow may fit a long holding period better than a short-term resale plan.
Build Your Personal Financial Snapshot
Before buying another home or converting your current residence into a rental, gather the numbers that determine how much flexibility you actually have:
- Estimated market value, mortgage payoff amount, and usable equity.
- Monthly household income, recurring debt, and fixed living expenses.
- Emergency savings separate from funds intended for a down payment.
- Credit profile and realistic borrowing capacity.
- Cash available for closing costs, repairs, furnishing, and reserves.
- Your expected holding period and willingness to manage uncertainty.
This exercise can prevent a common mistake: using all available cash to acquire a property and leaving too little for an unexpected HVAC repair, vacancy, deductible, or job change.
Use Plano and North Texas Data Without Chasing Headlines
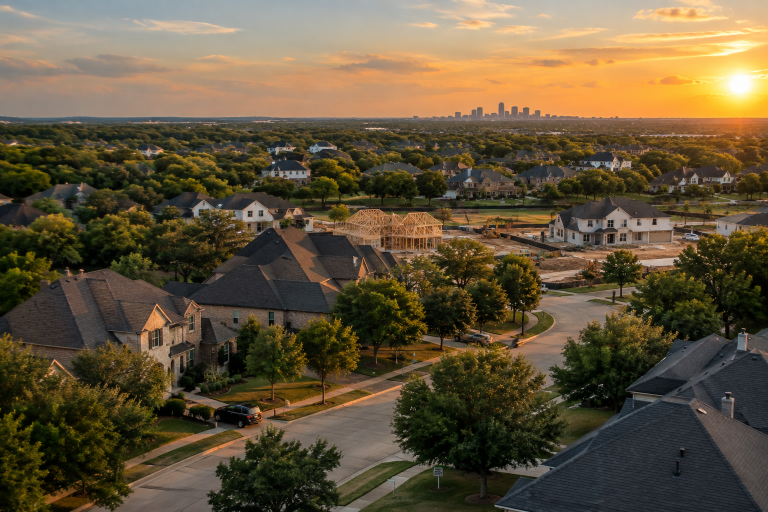
Metro-wide reports provide context, but they do not replace block-by-block research. Conditions can differ between an established Plano neighborhood, a newer Frisco subdivision, a McKinney home near active construction, and an urban Dallas rental. Compare recent closed sales, active competition, days on market, price reductions, rental listings, school boundaries, commute patterns, and planned development.
As of September 2026, statewide research reported expanding inventory, elevated mortgage rates, and slower price movement in some Texas markets. The Texas housing market research also noted that July inventory conditions and price movement varied by metro area, which is a reminder to verify current comparable properties before making an offer or setting a list price.
Choose the Property Role That Fits the Goal
Primary Residence or Move-Up Home
For an owner-occupant, affordability and flexibility usually come first. Consider total carrying costs, potential future resale demand, and whether the home can reasonably serve your household through the next stage of life. A move-up purchase should include selling costs, moving expenses, and the possibility of carrying two homes temporarily.
Rental, Commercial Property, or Land
A rental requires a plan for tenant turnover, maintenance, taxes, insurance, lease administration, and compliance. Commercial property adds lease structure, tenant concentration, and operating-expense considerations. Land or development opportunities call for careful review of zoning, utilities, access, drainage, and future demand. Each category can serve a different purpose, so avoid applying residential assumptions to every asset.
Create a Property-Level Profit and Loss Estimate
Estimate performance conservatively. Start with likely monthly rent or realistic resale proceeds, then subtract all recurring and irregular costs. Include principal and interest, property taxes, insurance, association dues, utilities paid by the owner, management fees, routine repairs, vacancy, leasing costs, and reserves for major items such as roofing, plumbing, exterior work, and HVAC replacement.
For example, if projected rent is $2,500 per month, do not assume all $2,500 is available to pay the mortgage. Set aside amounts for vacancy and maintenance before judging cash flow. Positive monthly income matters, but so do loan balance reduction, tax consequences, property condition, and the owner’s ability to hold through a slower leasing period.
Account for Taxes, Insurance, and Management
Two similarly priced North Texas homes can have very different ownership costs. Review tax estimates before offering, request insurance quotes early, and read homeowners association rules before planning a rental or major renovation. Homeowners should also confirm whether they qualify for exemptions. Texas property taxes are locally assessed and administered, and the state’s property tax exemption guidance explains that qualifying residence homesteads may receive exemptions from appraised value.
Professional property management may make sense for owners who live far away, own multiple units, or prefer help with screening, rent collection, inspections, maintenance coordination, vendor oversight, and reporting. Compare management fees against the time, knowledge, and operational responsibility required for self-management. Tax, legal, and financial questions should be reviewed with appropriately qualified professionals.
Connect Selling Decisions to the Next Move
When a sale will fund another purchase, focus on estimated net proceeds rather than the headline sale price. Account for mortgage payoff, concessions, repairs, closing costs, moving expenses, and temporary housing if needed. A purchase contingency, bridge financing option, or backup housing plan can reduce pressure when timing does not line up perfectly.
Create a Five-Year Review Schedule
- Review value estimates, loan balances, and insurance coverage annually.
- Update repair reserves and identify large maintenance items before they become urgent.
- Compare rental assumptions with current local listings and actual operating results.
- Reassess whether the property still supports the original household or investment goal.
- Revisit the plan after major changes in income, family circumstances, debt, taxes, or estate plans.
Common Questions
Is 2026 a good year to buy in North Texas?
The better question is whether a specific home fits your budget, timeline, and local market evidence. Higher borrowing costs and additional inventory can create tradeoffs rather than a universal answer.
Should I pay down my mortgage or save for another property?
Compare liquidity, interest costs, emergency reserves, and risk tolerance. The right choice depends on your full financial position, not a single rule.
How much reserve cash should a rental owner keep?
Keep reserves appropriate to the property’s age, condition, payment, insurance deductible, and expected repairs. A newer property and an older property may require very different cushions.
Conclusion
A durable real estate wealth plan does not require constant buying or aggressive risk. For Plano and North Texas owners, it begins with clear goals, honest numbers, local research, sensible reserves, and regular reviews. The strongest strategy is one that remains workable through changing rates, expenses, property conditions, and personal priorities.